
Families arranging a hospital bed, oxygen device, wheelchair or rehabilitation machine often ask whether health insurance will pay for the rental. In India there is no universal answer. Coverage depends on the specific policy wording, benefit structure, reason for use, claim type, authorisation and documents. A device being medically useful, prescribed or available for rent does not by itself make it reimbursable.
Quick answer
Do not assume that medical equipment rental is covered. Read the policy schedule, wording and Customer Information Sheet, then obtain a written answer from the insurer or authorised claims administrator for the exact item and situation. Ask whether the item falls under hospitalisation, home care, domiciliary treatment, OPD or a specific equipment benefit, and confirm rental versus purchase, limits, authorisation, supplier documents and the claim process.
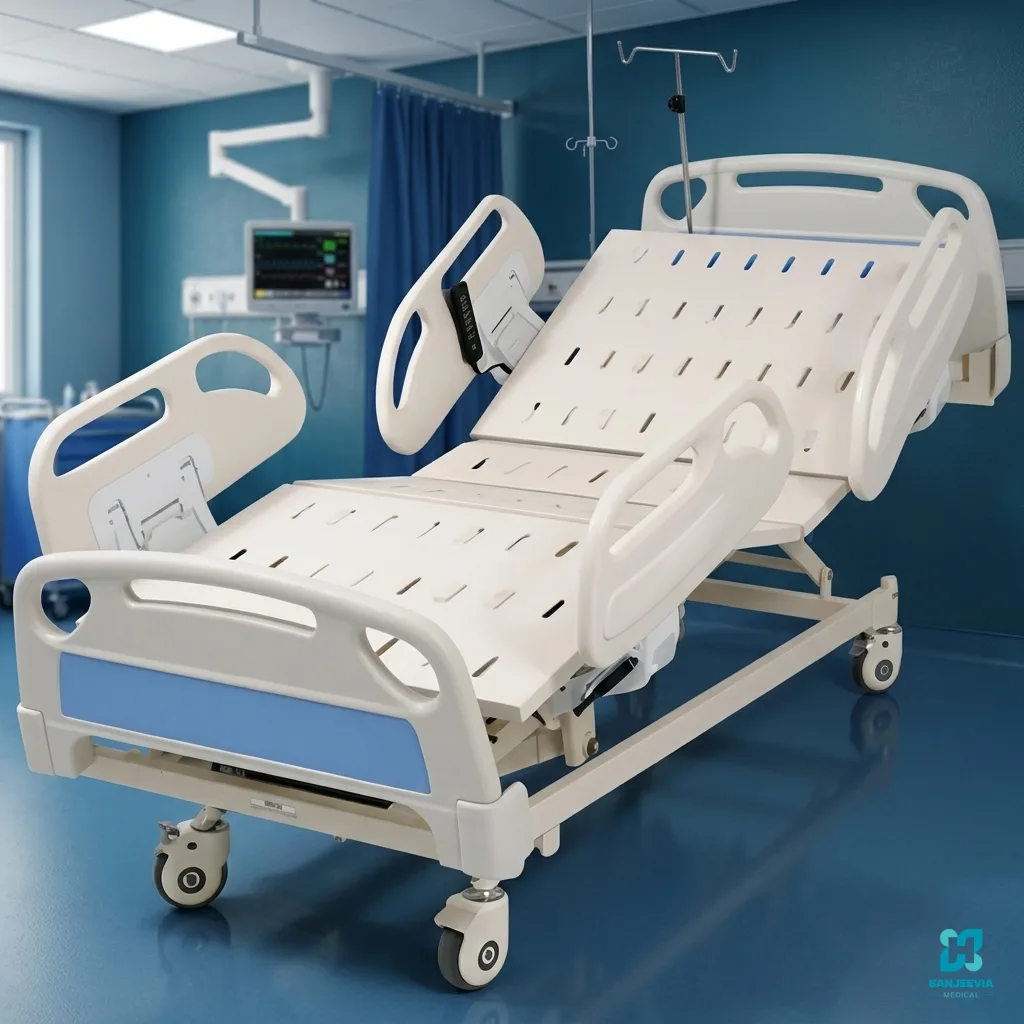
These are examples of equipment families may ask an insurer about. A Sanjeevia listing does not mean the item is covered by any policy, and Sanjeevia does not decide insurance claims.


Why the answer varies between policies
The Insurance Regulatory and Development Authority of India health-insurance page explains that health insurance pays according to the terms and conditions of the contract. It also describes the Customer Information Sheet as a plain-language summary of key features. Those documents, together with endorsements and the policy schedule, are the correct starting point.
One policy may cover specified home-care treatment but exclude equipment hired outside that episode. Another may reimburse eligible equipment only when it forms part of an approved claim. A third may have no relevant benefit. Sanjeevia supplies equipment and can provide applicable transaction documents, but it cannot interpret a policy for the insurer, promise reimbursement or influence a claim decision.
Eight questions to ask before renting
1. Which exact policy benefit could apply?
Ask the insurer to identify the benefit and clause, not simply answer “medical equipment is covered.” Possible headings include hospitalisation, pre-hospitalisation or post-hospitalisation, domiciliary treatment, home care treatment, OPD, consumables or a separate durable-equipment benefit. Similar words can have policy-specific definitions.
Use the full equipment name and purpose. “Machine for home” is too vague. State, for example, “rental of a three-function hospital bed for recovery at home after discharge,” then ask for the relevant clause in writing.
2. Is rental eligible, purchase eligible, both or neither?
A policy may treat hiring and purchasing differently. Ask whether reimbursement is based on the actual eligible rental period, a stated limit or another rule. Do not buy an item because rental is excluded, or rent because purchase is excluded, until the insurer has confirmed the actual terms.
Also ask whether the benefit applies to the main device, patient-specific accessories, consumables or none of them. Keep each category separate on your document checklist.
3. Must it be part of an approved treatment episode?
Ask whether equipment is eligible only when connected to an admissible hospitalisation, surgery or approved home-care treatment. Confirm the allowed time window and whether the treating doctor’s written recommendation must explain the medical need and expected duration.
The IRDAI health department lists home care, domiciliary hospitalisation, day care and OPD as treatment situations that policy documents should explain. This does not mean every policy pays every cost in those situations.
4. Is prior authorisation required?
Ask whether approval is required before rental starts, before it is extended or before a supplier is selected. Record the authorisation number, date, approved item, approved duration and any conditions. A telephone discussion without a reference may be difficult to establish later.
If equipment is needed urgently for discharge, ask what provisional documentation the insurer accepts and whether retrospective approval is possible under the policy. Do not delay clinically necessary discharge planning while assuming a claim will be approved. Discuss the care need and financial options separately.
5. Are there supplier, network or invoice requirements?
Confirm whether the supplier must be in a network, registered in a particular way or selected through the insurer. Ask what the invoice must show, whether a rental agreement is needed and whether tax details, serial number, delivery record or payment proof are required.
Sanjeevia can explain the documents it issues for an eligible order. Send the insurer’s checklist before booking so the family can identify any gap. An equipment provider should not alter a document to fit a claim description that does not match the transaction.
6. What limits and cost sharing apply?
Ask about sublimits, co-payment, deductible, room-category linkage, proportionate deductions and the maximum eligible duration. Also ask whether the equipment cost sits within the main sum insured or a separate benefit. Avoid calculating expected reimbursement from the full invoice alone.
Request a written example if the policy language is unclear, while recognising that final payment may still depend on claim assessment. Keep the insurer’s reply with the claim file.
7. Is the process cashless or reimbursement?
Do not assume that a cashless hospital claim makes a home-equipment rental cashless. Ask who pays the supplier initially, where the claim is submitted, which forms are required and how extensions or renewals are handled. Note submission deadlines and whether originals are required.
Keep copies of the policy documents, authorisation, prescription, discharge summary, medical-necessity note, rental agreement, invoices, payment records, delivery or collection record and correspondence. Share only information necessary for the claim through the insurer’s approved channel.
8. What happens if the claim is partly paid or rejected?
Ask for the decision and reasons in writing, linked to the policy clause. Follow the insurer’s grievance process first. IRDAI provides information on policyholder protection and grievance redressal. Keep dates, reference numbers and copies of every submission.
A supplier can correct a genuine invoice error or provide an available transaction record. It cannot certify insurance eligibility, rewrite the clinical reason or guarantee reversal of a claim decision.
Document checklist for the family
- Policy schedule, wording, Customer Information Sheet and endorsements
- Written benefit and authorisation response from the insurer or claims administrator
- Prescription or medical-equipment recommendation where required
- Discharge summary and approved treatment plan where applicable
- Supplier quotation or order details requested before approval
- Rental agreement, invoice, payment evidence and delivery record
- Serial or model information if the insurer specifically requires it
- Extension approvals for rentals continuing beyond the initial period
Before signing a rental document, review Sanjeevia’s medical equipment rental agreement checklist. For equipment selection, the Help Me Choose page can organise product questions, but it is not an insurance eligibility tool.
Frequently asked questions
Does a doctor’s prescription guarantee equipment-rental coverage?
No. A prescription may support medical need, but coverage still depends on the policy, benefit conditions, authorisation and claim assessment.
Is home-care treatment the same as equipment-rental coverage?
No. Home-care treatment is defined by the policy. Equipment may be included, limited or excluded, so ask about the exact item and clause.
Will a cashless hospital claim cover a home hospital bed automatically?
No. Confirm the home-equipment benefit and payment process separately. It may require reimbursement or may not be covered.
Can Sanjeevia confirm whether my insurer will pay?
No. Sanjeevia can describe the order and available documents. Only the insurer or authorised administrator can confirm eligibility and decide the claim.
What should I do before extending a rental?
Ask whether a fresh medical note or prior authorisation is required and obtain written approval before assuming the additional period will be eligible.
General information reviewed against IRDAI consumer material on 23 October 2026. This is not insurance, legal or financial advice. Policy wording and written insurer confirmation control the claim.
Next Read
Before booking equipment, use the Medical Equipment Rental Agreement Checklist.